
Preparing Your Financial Records from Fanash Family Law Before Filing for Divorce
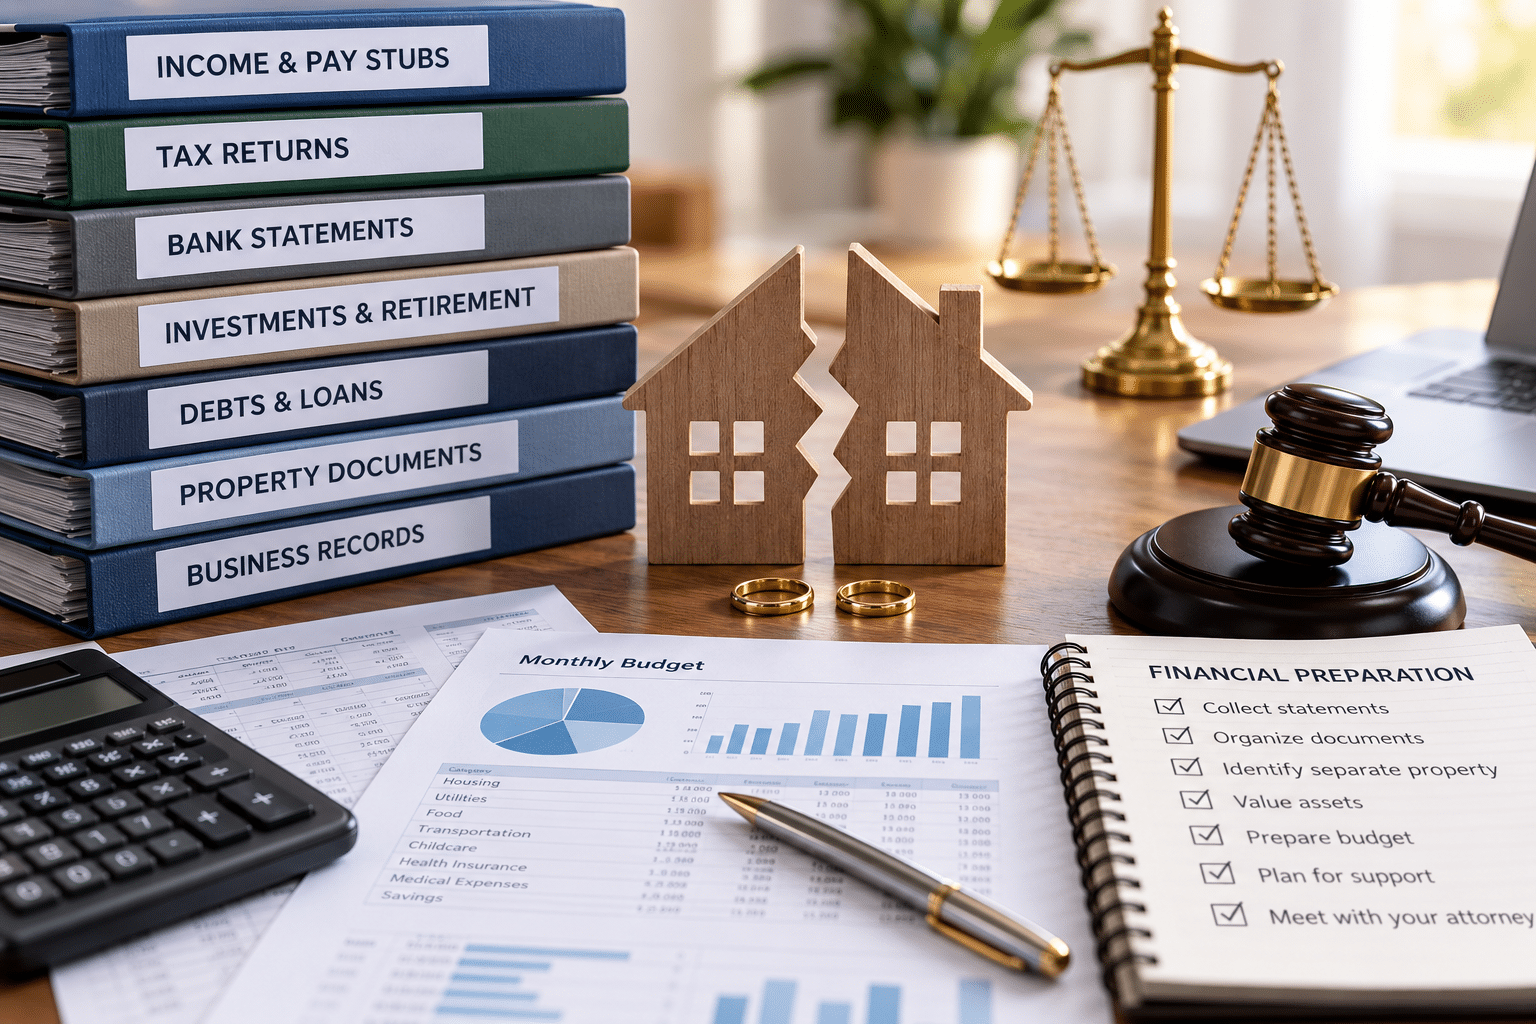
Divorce raises two parallel questions: How will you divide what you own and owe, and how will each household function afterward? The more clearly you can document income, assets, debts, and routine expenses, the easier it becomes to address those questions during negotiations, mediation, or court proceedings. Good records can also reduce the risk of surprises during discovery and help prevent avoidable disputes over classification, valuation, and support. This preparation is not about manipulating the process. It is about accuracy, traceability, and credibility, three qualities that help financial decisions in a divorce withstand careful review.
Define the Date of Separation and What It Means for Money
Start by identifying how your jurisdiction treats marital property and how the date of separation may affect financial issues, because the rules vary by state. In some jurisdictions, the date of separation can affect how earnings, contributions, debts, or property are characterized. At the same time, assets owned before marriage, gifts, and inheritances may be treated differently depending on the circumstances and whether you mixed funds. Gather bank, credit card, and investment statements covering the period around the separation date, and save pay stubs from the months before and after it. If you are unsure about the terms or stages you may encounter as your case begins, the overview at Fanash Family Law can help place these records in the context of the broader divorce process.
Compile Pay, Tax, and Account Records
Create a file that covers income, taxes, assets, and liabilities. Gather the last three years of tax returns with all schedules, W-2 forms, and 1099 forms, the most recent six to twelve months of pay stubs, and monthly statements for every checking, savings, credit card, brokerage, and retirement account. Include mortgage and HELOC statements, auto loan records, student loans, and personal lines of credit. Add property deeds, vehicle titles, and information about any life insurance policy with cash value. If you have an HSA or FSA, include plan statements and recent reimbursement records. For children’s expenses, collect childcare invoices, extracurricular activity receipts, and health insurance information showing who pays the premiums and other costs.
If a business is involved, assemble profit and loss statements, balance sheets, general ledgers, K-1 forms, depreciation schedules, and reports showing accounts receivable and payable. These records can help clarify income available for support and provide information relevant to business valuation, including tangible assets and potential goodwill. Export original PDFs or CSV files rather than relying only on screenshots so transaction dates and line items remain clear. Name each file using the institution, the last four digits of the account, and the statement month. These small organizational habits can simplify discovery and make missing documents easier to identify.
Identify and Protect Separate Property and Avoid Commingling
Separate property claims often depend heavily on documentation. If you received an inheritance, maintained a retirement account from before marriage, or owned a home before the marriage, preserve the available paper trail. Useful documents may include closing statements, account opening records, wire confirmations, and rollover or transfer forms. Avoid mixing funds unnecessarily when you are trying to preserve a clear record of their source, and discuss significant transfers with your attorney because property classification rules vary by jurisdiction.
Consider a common scenario. Someone deposits a $40,000 inheritance into a joint account and then uses that account for a kitchen renovation, groceries, and school expenses. Determining what portion remains traceable to the original inheritance may require detailed transaction tracing and professional analysis, increasing both complexity and cost. Maintaining organized records showing the source, date, movement, and use of funds can make later financial analysis much easier.
Valuing Complex Assets: Homes, Pensions, RSUs, and Small Businesses
Some assets require more detailed valuation. For the marital home, a professional appraisal may provide a stronger foundation than an online estimate, particularly when the property has unusual features or comparable sales vary widely. The valuation date can also matter because changing market conditions may affect equity during a lengthy case. For pensions and defined benefit plans, obtain a plan summary and current benefit estimate. Dividing certain retirement plans may require a Qualified Domestic Relations Order, and individual plans may use different formulas based on service years, compensation, and other factors.
For RSUs and stock options, track grant dates, vesting schedules, forfeiture provisions, and tax withholding when shares vest. Depending on applicable law and the facts of the case, unvested compensation may require additional analysis to determine whether and how to divide it.
Tradeoffs are common. One spouse may want to keep the house in exchange for receiving less from a retirement account, but liquidity, taxes, maintenance costs, and refinancing ability all matter. A house brings property taxes, insurance, repairs, and ongoing upkeep, while pre-tax retirement assets may create future tax consequences. For example, a parent may want to remain in the home for school stability but may not qualify to refinance independently. Options could include selling the property, negotiating a temporary occupancy arrangement, or creating a structured buyout, depending on legal advice and financial feasibility.
Small businesses add another layer of complexity. A forensic accountant may review personal and business expenses, normalize owner compensation, examine cash flow, and evaluate goodwill. Accurate books can make it easier to distinguish legitimate business expenses from personal spending and provide a more reliable basis for valuation and support discussions.
Budget, Temporary Orders, and Support Worksheets
Temporary orders can affect finances and household arrangements while a divorce is pending, and accurate budgets can be important during that stage. Prepare an Income and Expense Declaration or similar financial affidavit using documented figures for rent or mortgage payments, utilities, childcare, health insurance premiums, medical costs, transportation, and recurring subscriptions. Review several months of bank and credit card statements to calculate reasonable averages for variable expenses.
Child support calculations may consider factors such as income, parenting arrangements, childcare expenses, and health insurance costs, although the exact formula depends on state law. Consider a self-employed photographer who receives irregular 1099 income and occasional cash payments. If deposits aren’t supported by invoices, expense records, and other documentation, calculating reliable income becomes more difficult. Organized records allow a court, mediator, or attorney to work from documented information instead of estimates.
Two common mistakes can create unnecessary complications. First, moving substantial funds without clear documentation may raise questions about where the money went and why. If you must transfer funds for legitimate expenses, keep records showing the amount, date, purpose, and destination, and consult your attorney when appropriate. Second, making major unilateral changes to household finances or parenting arrangements during a pending case may create additional disputes. Before changing important financial obligations or family arrangements, consider obtaining legal advice about any existing court orders or local rules.
Keep Records Organized Through the Final Steps
Once you have assembled your financial records, bring them to an initial consultation in an organized binder or a clearly labeled secure digital folder. A legal professional can use those materials to identify missing information, prepare appropriate discovery requests, evaluate settlement options, and develop a more realistic timeline for the case.
Organization remains important after a final agreement or court order. You may need to prepare and submit retirement division documents, update vehicle titles and deeds, close or manage joint credit accounts, and review beneficiary designations in accordance with the final orders and applicable law. Keeping accurate records from the beginning can make these later tasks easier to complete and reduce the risk of financial misunderstandings.
Preparing financial records before filing for divorce is ultimately about creating a clear picture of the household’s financial life. Complete tax records, account statements, debt information, property documents, business records, and realistic expense figures give attorneys, mediators, and courts better information. Maintaining that documentation throughout the process can also reduce confusion when assets are transferred, and obligations are implemented. The more organized and traceable the financial record is, the easier it becomes to make informed decisions and move through the process with fewer avoidable surprises.
About the Author
Fred Campos is a father, custody advocate, and host of the Daddy Got Custody podcast. He shares practical parenting and child custody tips to help parents navigate family court with confidence.
Join Our Newsletter

How Legal Services Protect Your Rights in Court
California residents navigating the court system often face complex legal challenges that can significantly impact their rights and future. Legal services play a critical role in protecting individuals throughout every stage of a case, from preparing evidence and...

When to Involve a Lawyer in a Divorce Case
Divorce is often one of life’s most challenging experiences, bringing emotional and financial upheaval. Knowing when to involve a lawyer can make the process less stressful and ensure decisions are made carefully. Many situations, such as disputes over finances, child...

What Types of Cases Does a Family Lawyer Handle?
In New Haven, Connecticut, family law encompasses a broad spectrum of legal matters that directly impact individuals and families. According to the Connecticut Judicial Branch, in 2024, the New Haven Judicial District reported 2,971 new family cases, highlighting the...
Tips for Dealing with a Struggling Marriage
Being married is something to be proud of, but also requires a lot of work. Not all days will be good, and you may go through tough situations together. Over time, there may be a strain on your marriage, and you may not be getting along as well as you did previously....
Tips To Create a Kid Friendly Wedding
Are you planning a wedding over the next few months? Are you considering remarrying with kids? This is a stressful time for anyone, let alone people who have small children in their families who are going to be attending the event. Of course, this adds a layer of...
Menstruation While Breastfeeding: What’s Normal and What to Expect
Menstruation while breastfeeding is different for every mom—it may return in months or take over a year. This article explains why it can be delayed, when it usually comes back, how it may affect milk supply, and the difference between spotting and a full...